The digital-asset market has produced a large number of new trading platforms that promote artificial intelligence, Web3 infrastructure, derivatives trading, and other technology-focused services. ZOZOTRADE Exchange is one such platform.
ZOZOTRADE presents itself as a digital-asset trading platform offering spot and derivatives products, AI-assisted trading tools, and a technology-oriented trading environment. Its website and promotional materials also reference U.S. regulatory registrations, including a FinCEN Money Services Business (MSB) registration.
A proper assessment, however, requires separating three different questions:
Does a corporate or regulatory record exist?
What does that record actually authorize or establish?
Does the record correspond to the exchange business that users are being asked to use?
The evidence reviewed for this report shows that some of ZOZOTRADE's regulatory claims have a factual basis, but those records should not automatically be interpreted as approval or licensing of the ZOZOTRADE cryptocurrency exchange itself.
This report therefore focuses on verifiable records rather than attempting to determine, solely from the available information, whether the platform is fraudulent or legitimate.
1. Domain History: A Relatively Recent Trading Brand
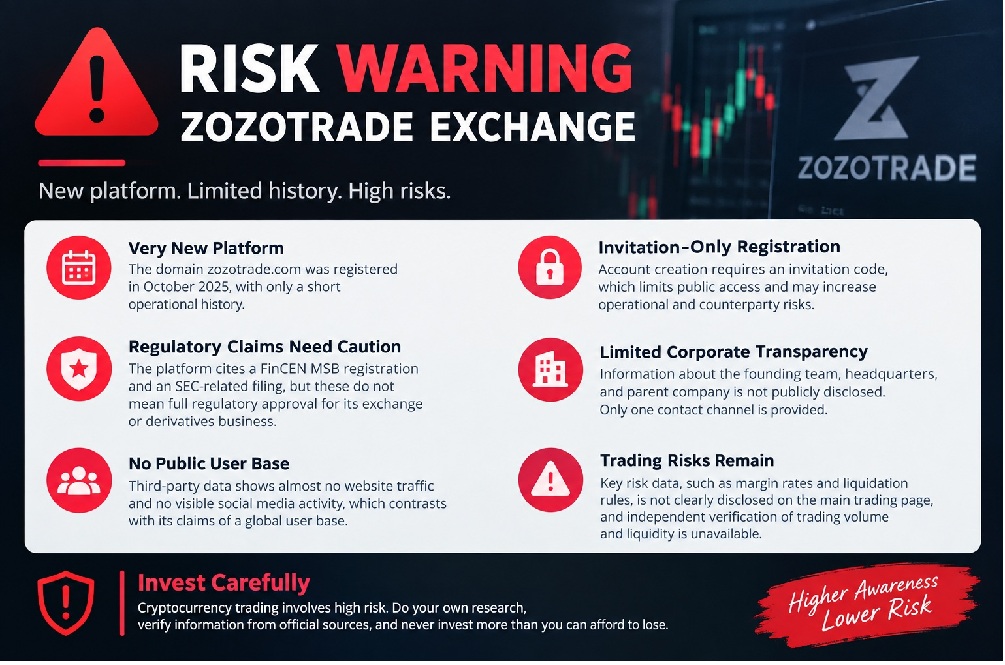
Public WHOIS information records the creation of zozotrade.com on October 8, 2025.
A publicly accessible domain record shows:
Domain: zozotrade.com
Creation date: October 8, 2025
Registrar: Gname.com Pte. Ltd.
Original expiration date: October 8, 2026
The same domain record currently shows a later update date of April 22, 2026, meaning that the earlier November 27, 2025 update cited in some December 2025 reports is no longer the latest domain record.
Evidence
The publicly indexed WHOIS information identifies the creation date as:
2025-10-08T06:37:20Z
This establishes that the current zozotrade.com domain is relatively new.
However, domain age should not be treated as proof of wrongdoing. A newly established domain can belong to a legitimate newly launched company. The relevant issue is instead the discrepancy, if any, between the platform's claimed scale and the amount of independently verifiable operating history.
Assessment:
The domain history establishes a relatively short public digital history. It does not, by itself, establish misconduct.
2. FinCEN MSB Registration: What It Does and Does Not Mean
ZOZOTRADE has publicly referenced a U.S. Money Services Business registration with the Financial Crimes Enforcement Network (FinCEN), identifying the MSB number as:
31000311156365
The existence of an MSB registration should be interpreted carefully.
FinCEN's own explanation is particularly important. The agency states that inclusion in its MSB Registration database is not a recommendation, certification of legitimacy, or endorsement of the business.
FinCEN also explains that information on the MSB registration website is provided by the registrant and that FinCEN does not independently verify the information submitted by the MSB.
Why this matters
An MSB registration and a securities or derivatives license are not interchangeable concepts.
An MSB registration can be relevant to businesses involved in activities covered by the Bank Secrecy Act and associated AML requirements. It does not, by itself, establish that a company has received authorization to operate every type of financial market or trading product that it may advertise.
Therefore, the following statements should not be treated as equivalent:
"Registered as an MSB"
and
"Approved by the U.S. government to operate a cryptocurrency exchange."
They describe materially different regulatory concepts.
Evidence
FinCEN explicitly states:
MSB registration is not a recommendation;
MSB registration is not a certification of legitimacy;
MSB registration is not a government endorsement;
information is supplied by the registrant and is not independently verified by FinCEN.
Assessment:
The MSB reference is a real regulatory concept, but its presence should not be presented as a general government approval or safety certification for ZOZOTRADE Exchange.
3. The SEC Record: An Important Correction
The original version of this analysis stated that ZOZOTRADE had no SEC-related registration.
That conclusion is too broad.
A search of the SEC's Investment Adviser Public Disclosure system identifies:
ZOZOTRADE INC
CRD: 339009
SEC File No.: 802-134767
Status: Exempt Reporting Adviser
ERA Status: Active
Effective date: October 16, 2025
These details appear in the SEC's adviser database.
The underlying Form ADV filing also identifies ZOZOTRADE INC and provides a principal office address of:
142 Lafayette Street
Newark, New Jersey 07105
United States
The filing identifies the company as an exempt reporting adviser and provides CRD number 339009 and SEC file number 802-134767.
This is significant because it demonstrates that there is a genuine SEC-related regulatory filing associated with an entity named ZOZOTRADE INC.
However, another distinction is necessary.
ERA status is not the same as SEC registration as a broker-dealer or approval as a cryptocurrency exchange
The SEC explains that exempt reporting advisers are advisers that are not required to register as investment advisers because they rely on specified exemptions, although they still file reports through the SEC system.
Separately, the SEC explains that broker-dealers generally must register with the SEC and satisfy applicable self-regulatory organization requirements before conducting broker-dealer business.
The SEC also explains that operating a platform that enables trading of securities can be an activity relevant to broker-dealer regulation, depending on the facts and circumstances.
Therefore:
The existence of ZOZOTRADE INC as an SEC-reporting exempt adviser should not automatically be interpreted as SEC approval of ZOZOTRADE Exchange's spot or derivatives trading operations.
This is one of the most important distinctions in evaluating the platform.
Assessment:
There is a verifiable SEC-related record for ZOZOTRADE INC. The record should be described accurately as an Exempt Reporting Adviser filing/status, rather than as blanket SEC authorization of a cryptocurrency exchange.
4. Corporate Identity and the Exchange Entity
The SEC Form ADV record provides useful corporate information that was not clearly established in earlier versions of this report.
The filing identifies:
Legal name: ZOZOTRADE INC
CRD: 339009
SEC file number: 802-134767
Principal office: 142 Lafayette Street, Newark, New Jersey 07105
Telephone: +1 (647) 874-4331
This evidence materially changes the earlier conclusion that there was no identifiable corporate information whatsoever.
At the same time, an important verification question remains:
Is the SEC-reporting ZOZOTRADE INC the same legal entity that operates ZOZOTRADE Exchange?
The name similarity alone is not sufficient to answer this question.
A professional due-diligence process should establish the legal relationship between:
ZOZOTRADE INC;
the entity identified in the FinCEN MSB registration;
the operator of zozotrade.com;
the operator of the trading infrastructure;
and any entity responsible for holding or controlling customer assets.
Until these relationships are clearly documented, the existence of one regulatory record should not automatically be attributed to every activity carried out under the ZOZOTRADE brand.
Assessment:
There is substantially more corporate and regulatory information available than the original report suggested, but the precise relationship between the regulatory entity and the exchange operation remains an important point for verification.
5. Claims of Global Scale vs. Verifiable Market Footprint
ZOZOTRADE's promotional materials describe the platform as a global digital-asset trading service.
Earlier reports also highlighted claims relating to a large international user base and compared those claims with very low third-party website-traffic estimates.
This type of comparison can be useful, but traffic analytics must be treated cautiously.
Third-party traffic-estimation services do not have direct access to a company's complete internal user database. A low estimated web-traffic number therefore cannot prove that a platform has no users.
Likewise, website traffic alone cannot establish whether trading activity exists through:
direct links;
mobile applications;
private referral channels;
API connections;
regional websites;
or other sources.
The stronger conclusion is therefore narrower:
There is insufficient publicly verifiable evidence in the sources reviewed to independently confirm the scale of the user base claimed in promotional materials.
That is a due-diligence issue rather than proof of fraud.
Assessment:
The platform's claimed scale should be independently verified through transparent metrics such as trading volume, proof of reserves, identifiable market-making arrangements, audited financial statements, or other independently verifiable operational data.
6. Registration and Invitation-Code Requirements
Another feature identified in previous examinations of the platform is the use of an invitation-code requirement during registration.
An invitation-only registration system is not inherently illegal or fraudulent. Financial and technology platforms may use referral systems for marketing, regional onboarding, or controlled product launches.
Nevertheless, when evaluating a trading platform, restricted access creates an additional verification question:
Why is access restricted, and what entity is responsible for users who enter through the referral system?
This becomes particularly relevant if users are introduced to the platform through:
Telegram;
WhatsApp;
private investment groups;
individual "account managers";
or referral agents.
The presence of an invitation code therefore should be classified as a due-diligence factor, rather than presented as evidence that the platform is deliberately avoiding regulators.
The original claim that invitation-only registration is designed to "avoid automated regulatory bots" is speculative and should not be included without direct evidence.
Assessment:
Invitation-based onboarding is unusual enough to warrant additional questions about customer acquisition and account responsibility, but it is not proof of misconduct.
7. Transparency of Management and Ownership
One of the more important remaining questions concerns the relationship between the legal entity and the public-facing exchange.
The SEC Form ADV provides identifiable corporate information for ZOZOTRADE INC, which is an improvement over the impression created by earlier reports.
However, public-facing exchange information should still be examined for:
named directors and executives;
beneficial ownership;
corporate registration;
audited financial statements;
custody arrangements;
banking relationships;
insurance;
proof of reserves;
market-making arrangements;
legal terms;
jurisdictional restrictions;
and the legal entity responsible for customer assets.
A regulatory filing for an exempt adviser does not, by itself, answer these exchange-specific questions.
Assessment:
Corporate disclosure is more substantial than initially reported, but exchange-level transparency remains the key issue to verify.
8. Trading Products and Risk Disclosure
ZOZOTRADE presents trading functionality associated with cryptocurrency spot and derivatives products.
Previous examinations identified BTC/USDT perpetual-contract functionality and a TradingView-based charting interface.
A professional evaluation should distinguish between the existence of a trading interface and evidence of a functioning, independently verifiable market.
A professional exchange review should ideally examine:
actual order-book depth;
independently verifiable trading volume;
bid/ask spreads;
funding rates;
leverage limits;
maintenance-margin schedules;
liquidation mechanisms;
insurance-fund policies;
custody arrangements;
withdrawal limits;
withdrawal processing;
trading fees;
and market-surveillance procedures.
The existence of charts, order books, and trading screens demonstrates that the platform has built a trading interface. It does not independently establish the quality, liquidity, or external settlement of the underlying market.
9. Press Releases and Self-Reported Regulatory Claims
On December 16, 2025, ZOZOTRADE published a press release stating that it had completed FinCEN MSB registration and describing its regulatory alignment in the United States. The release also referred to an SEC-related registration and positioned these developments as part of its compliance framework.
This announcement is useful evidence of what ZOZOTRADE itself claims.
However, company press releases should be categorized as self-reported information, rather than independent regulatory confirmation.
The appropriate verification process is therefore:
Company statement → government database → exact legal entity → scope of authorization
rather than:
Company statement → presumed regulatory approval
This distinction is particularly important when a platform uses terms such as "regulated," "registered," "compliant," or "U.S. registered."
10. What the Available Evidence Actually Establishes
Based on the sources reviewed, the following conclusions can currently be supported.
Established or independently documented
1. The zozotrade.com domain was created on October 8, 2025.
Public domain records support this date.
2. ZOZOTRADE INC appears in the SEC/IAPD system.
The SEC record identifies ZOZOTRADE INC as an Exempt Reporting Adviser with CRD 339009 and SEC file number 802-134767.
3. The SEC filing provides a Newark, New Jersey address.
The Form ADV identifies 142 Lafayette Street, Newark, NJ 07105 as the principal office.
4. FinCEN MSB registration has been publicly claimed by ZOZOTRADE.
The platform has cited MSB number 31000311156365, while FinCEN explains that MSB listing is not government endorsement or certification of legitimacy.
5. An SEC ERA record does not automatically establish that the cryptocurrency exchange itself is SEC-approved.
The regulatory category and scope need to be examined separately.
11. What Has Not Been Independently Established
Several important questions remain open.
Exchange authorization
The available SEC record establishes an exempt-reporting-adviser filing for ZOZOTRADE INC. It does not, by itself, establish that zozotrade.com is a registered U.S. securities exchange, broker-dealer, or derivatives exchange.
Relationship between entities
It remains necessary to establish whether the entity named in the SEC filing is legally identical to, owns, controls, or provides services to the entity operating the exchange.
Customer-asset custody
The reviewed public records do not by themselves establish where customer cryptocurrency is held, who controls private keys, or whether customer assets are segregated.
Independent trading activity
The existence of a trading interface does not independently verify the volume, liquidity, or settlement of transactions taking place on the platform.
Financial condition
The reviewed materials do not establish audited financial statements, independently verified reserves, or a comprehensive financial-responsibility framework for the exchange.
User-base claims
The platform's claimed scale should not be accepted solely on the basis of promotional statements. Independent evidence would be required to establish the number of active users or the actual scale of trading activity.
12. Overall Assessment
The evidence presents a more nuanced picture than a simple "regulated" or "unregulated" classification.
On one hand, ZOZOTRADE is not simply an anonymous website with no identifiable regulatory footprint. There is an SEC/IAPD record for ZOZOTRADE INC, and the company has publicly identified a FinCEN MSB registration.
On the other hand, those records should not automatically be interpreted as comprehensive regulatory approval of the ZOZOTRADE cryptocurrency exchange.
The most important distinction is between the existence of a regulatory filing and the scope of activities covered by that filing.
FinCEN explicitly warns that MSB registration is not a certification of legitimacy or government endorsement.
Similarly, the SEC record identifies ZOZOTRADE INC as an Exempt Reporting Adviser rather than establishing, on its face, that the entity operates an SEC-registered cryptocurrency exchange or broker-dealer.
Therefore, the most defensible conclusion at this stage is:
ZOZOTRADE has identifiable regulatory records, but the available evidence does not establish that those records constitute comprehensive authorization or regulatory oversight of the entire cryptocurrency exchange operation advertised through zozotrade.com.
For users evaluating the platform, the central issue is therefore not simply whether ZOZOTRADE has an MSB number or an SEC record. The more important questions are which legal entity operates the exchange, what products that entity is legally authorized to provide, where customer assets are held, how trading activity is independently verified, and what protections apply if the platform becomes insolvent or withdrawals are suspended.
Until those questions can be independently answered, ZOZOTRADE should be treated as a platform requiring enhanced due diligence, rather than relying solely on its regulatory terminology or promotional materials.
Evidence and Primary Sources
FinCEN – MSB Registration Website
FinCEN explains the purpose and limitations of MSB registration and expressly states that registration is not a recommendation, certification of legitimacy, or government endorsement.SEC / Investment Adviser Public Disclosure – ZOZOTRADE INC
SEC/IAPD record identifying ZOZOTRADE INC, CRD 339009, SEC File No. 802-134767, and ERA status.SEC Form ADV – ZOZOTRADE INC
The underlying filing provides the company's legal name, CRD number, SEC file number, and Newark, New Jersey principal-office information.SEC – Broker-Dealer Registration Guide
The SEC explains the registration framework applicable to broker-dealers and related market activities.Public WHOIS / Domain Record
The publicly indexed domain record identifies October 8, 2025 as the creation date for zozotrade.com.ZOZOTRADE's December 16, 2025 Press Release
The company's own announcement concerning its FinCEN MSB registration and regulatory positioning. This source should be treated as self-reported corporate information rather than independent regulatory certification.
Important Methodological Note
This report does not determine whether ZOZOTRADE is a scam or whether individual users will experience losses. Such conclusions require substantially more evidence, including transaction records, custody information, corporate ownership documentation, withdrawal testing, regulatory correspondence, and potentially law-enforcement or court records.